Squeezing Neoclouds Pushes NVIDIA Back Toward Its Rivals
Squeezing Neoclouds Pushes NVIDIA Back Toward Its Rivals
NVIDIA has tightened financing conditions for Neocloud customers, requiring them to provide more equity capital, as ultra-large customer revenue grew by 71% to $60.1 billion and non-ultra-large customer revenue grew nearly threefold to $47.5 billion. NVIDIA holds $102 billion in cloud and data center leasing commitments, of which $32 billion are directly with Neocloud, while also facing competition pressure from custom chips for ultra-large customers.
NVIDIA’s hardest strategic problem is not demand : it is choosing which customer to feed.1
Hyperscalers like Google, Amazon, Microsoft & Meta buy $60.1b of NVIDIA hardware each quarter while racing to replace it with their own custom silicon. Neoclouds & frontier labs buy $47.5b & build no competing chips, yet rely on NVIDIA’s balance sheet to scale.
After climbing to a 45% share of Data Center revenue last quarter, non-hyperscaler share ticked down to 44% in Q3 just as NVIDIA signaled tighter financing terms.2
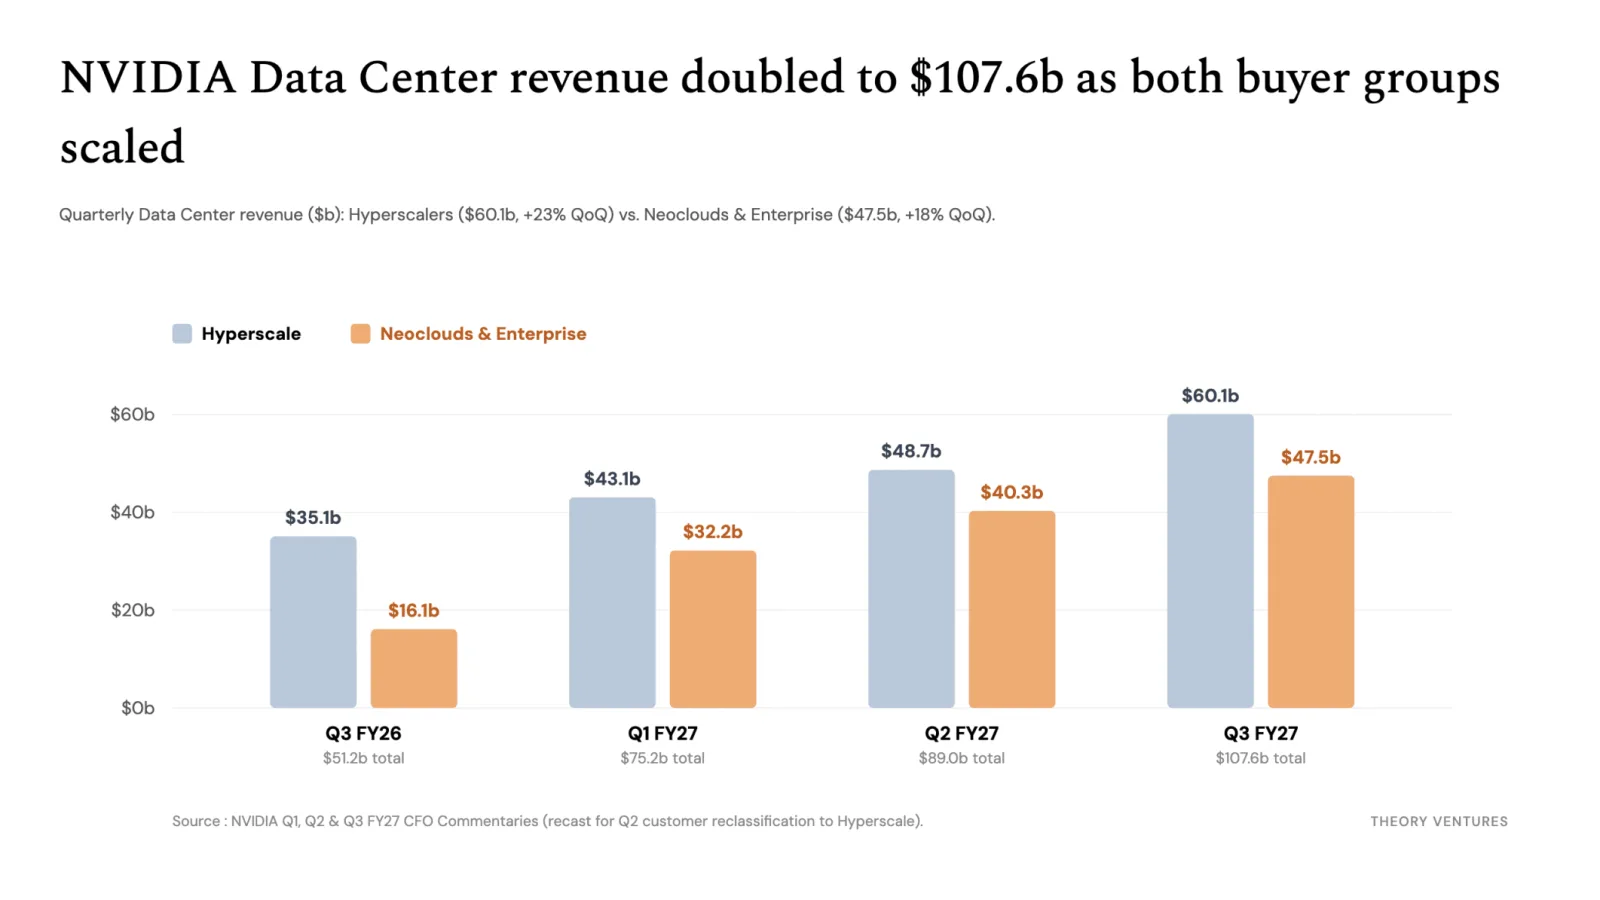
Hyperscale revenue grew 71% year over year to $60.1b, while neocloud & enterprise revenue nearly tripled to $47.5b on strong Vera Rubin shipments.2
“AI Clouds, Industrial & Enterprise revenue of $47 billion increased 18% sequentially & nearly tripled year-over-year.”
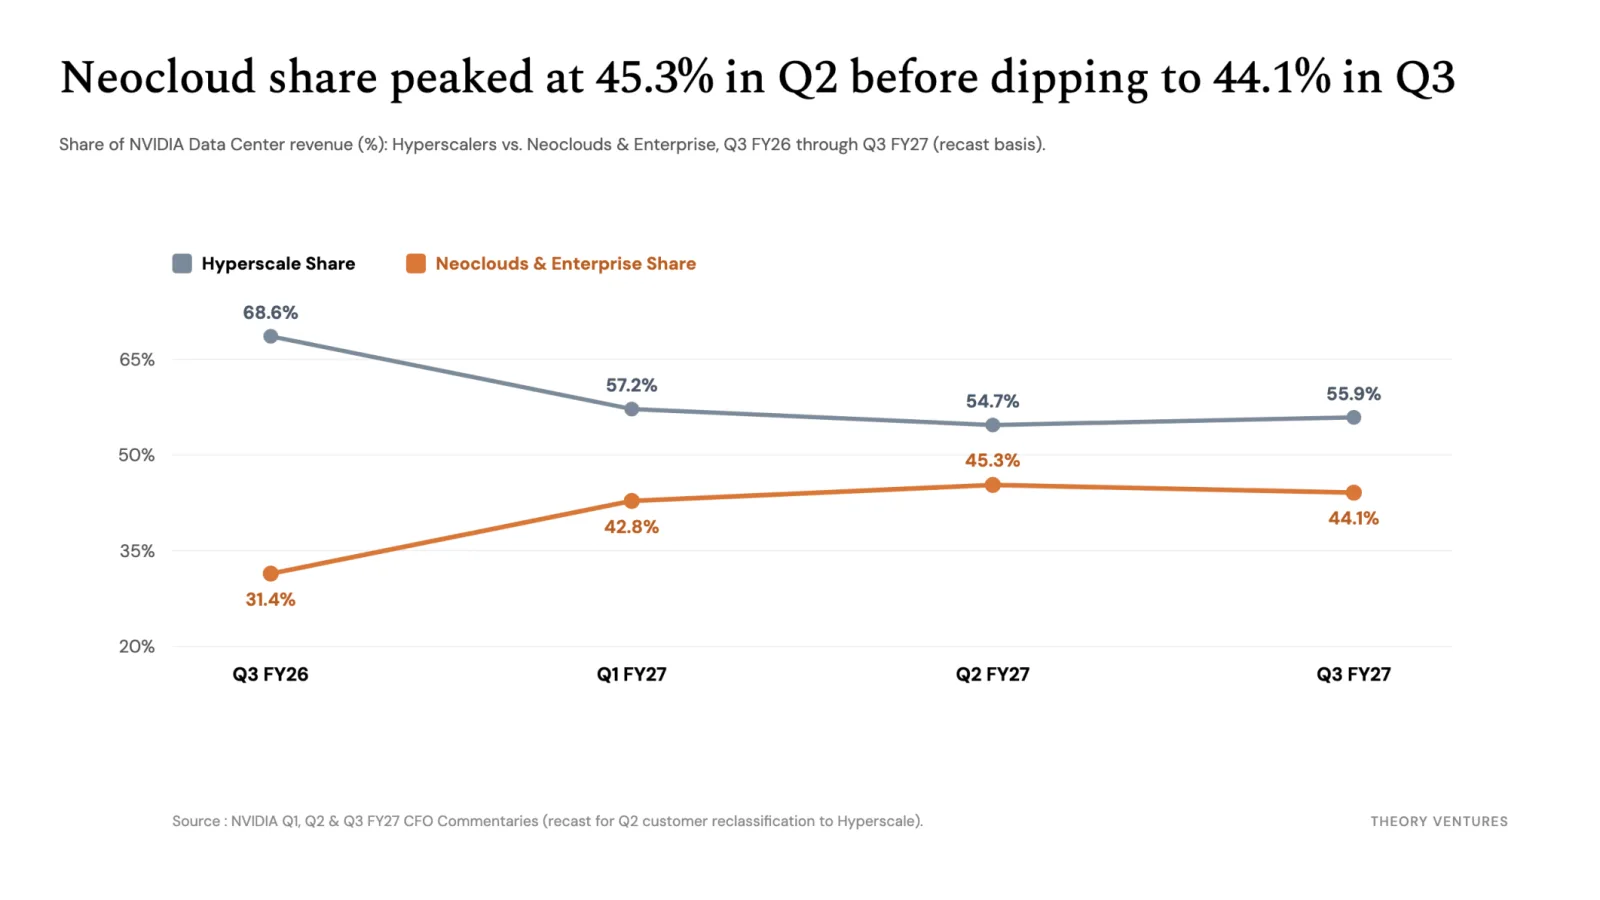
Yet NVIDIA is tightening the bar on neocloud financing. It holds $102b in cloud & data center lease commitments, including $32b directly with neoclouds, alongside $390b in purchase commitments.2 Interim CEO & CFO Colette Kress laid down a firmer line, demanding operators bring both powered shells & their own capital :
“We have supported the development of this ecosystem, & we will continue to be disciplined & selective in our support.”
Because neoclouds lack hyperscaler cash flows, a more selective backstop could moderate growth for smaller, capital-constrained operators.3
A diversified buyer base is NVIDIA’s best defense against hyperscaler custom silicon. Squeezing neoclouds hands that leverage right back to Google, Amazon, Microsoft & Meta.
-
NVIDIA Corporation, NVIDIA Announces Financial Results for Third Quarter Fiscal 2027, November 17, 2026 : total revenue $115.8b (+103% YoY, +20% QoQ), Data Center revenue $107.6b (+110% YoY, +21% QoQ), Q4 FY27 guidance $130.0b & FY28 growth outlook raised from 70% to 75%. ↩︎
-
NVIDIA Q3 FY27 CFO Commentary & Earnings Call Transcript (Colette Kress), November 17, 2026 : Hyperscale $60.1b (+71% YoY, +23% QoQ) vs. AI Clouds, Industrial & Enterprise $47.5b (+195% YoY, +18% QoQ) ; $20b in first-quarter Vera Rubin shipments ; $32b in direct neocloud agreements out of $102b total cloud & DC leases ; $390b purchase commitments. ↩︎ ↩︎ ↩︎
-
CNBC, Analysts react to Nvidia’s first earnings without CEO Jensen Huang, November 18, 2026, quoting Citi (
Buy, $225) & Bernstein (Market Perform, $200) on NVIDIA’s more measured commentary around neocloud financing & backstops. ↩︎
Source: Tomasz Tunguz · tomtunguz.com