Anthropic S-1 Analysis: How 7 Key Metrics Stack Up
Anthropic S-1 Analysis: How 7 Key Metrics Stack Up
Anthropic filed its S-1 this week, with revenue in the first half of 2026 reaching 16.3 billion USD, 14 times the 1.2 billion USD in the same period in 2025, exceeding three times the full-year revenue of 4.6 billion USD in 2025 in just six months.
Same story — featured version shown《Anthropic files S-1 with SEC, plans NASDAQ IPO》
Same story12 other outlets also reported this
- Anthropic Newsroom··First
- Tomasz Tunguz··+8 h 0 min·Reading now
Anthropic S-1 Analysis: Seven Key Metrics Compared with OpenAI
- 36Kr · AI··+19 h 34 min
Anthropic is reported to submit an S-1 filing, still planning to go public in mid-November
- 36Kr · AI··+21 h 7 min
- ITHome · AI··+21 h 30 min
Anthropic filed an IPO application with the Nasdaq, with the stock code ANT
- The Verge · AI··+21 h 33 min
Anthropic has submitted an S-1 to plan to list on the NASDAQ with ANT
Adds:Net loss of 807 billion USD
- ITHome · AI··+22 h 19 min
Anthropic submits S-1 registration file to SEC for Nasdaq listing
- TechCrunch · AI··+22 h 35 min
Anthropic officially filed its IPO application with the stock code ANT
- QbitAI··+24 h 7 min
- TechCrunch · AI··+24 h 50 min
Anthropic IPO Filing Discloses Enterprise Customer Retention Strategy
- The Verge · AI··+25 h 10 min
- MIT Technology Review · AI··+25 h 46 min
- The Decoder··+27 h 15 min
Anthropic files S-1 prospectus, revenue hits new high but computing power commitments are heavy
- ITHome · AI··+31 h 54 min
- 36Kr · AI··+32 h 8 min
- ITHome · AI··+33 h 28 min
Anthropic submits its IPO prospectus, boosting Asian chip stocks
- Ars Technica · AI··+2 d
Anthropic's IPO claims its AI could be used for extortion, creating consciousness, and ending humanity.
- ITHome · AI··+3 d
Anthropic's IPO filing discloses multi-platform computing power layout
- 36Kr · AI··+3 d
Anthropic's new share subscription slots are scarce, with Asian investors turning to indirect targets for investment.
In order of publication · later reports are added as they appear · Compared by AI from each outlet’s title and summary
Anthropic filed their S-11 this week, the largest AI listing yet.
Founded in 2021 by Dario & Daniela Amodei, the company has grown from a research lab into the second-largest model developer, selling Claude to more than 11,900 customers who spend over $100,000 a year. The comparisons below set the reported OpenAI figures2 against Anthropic’s derived gross margin3, adjusted operating margin4 & compute commitments5.
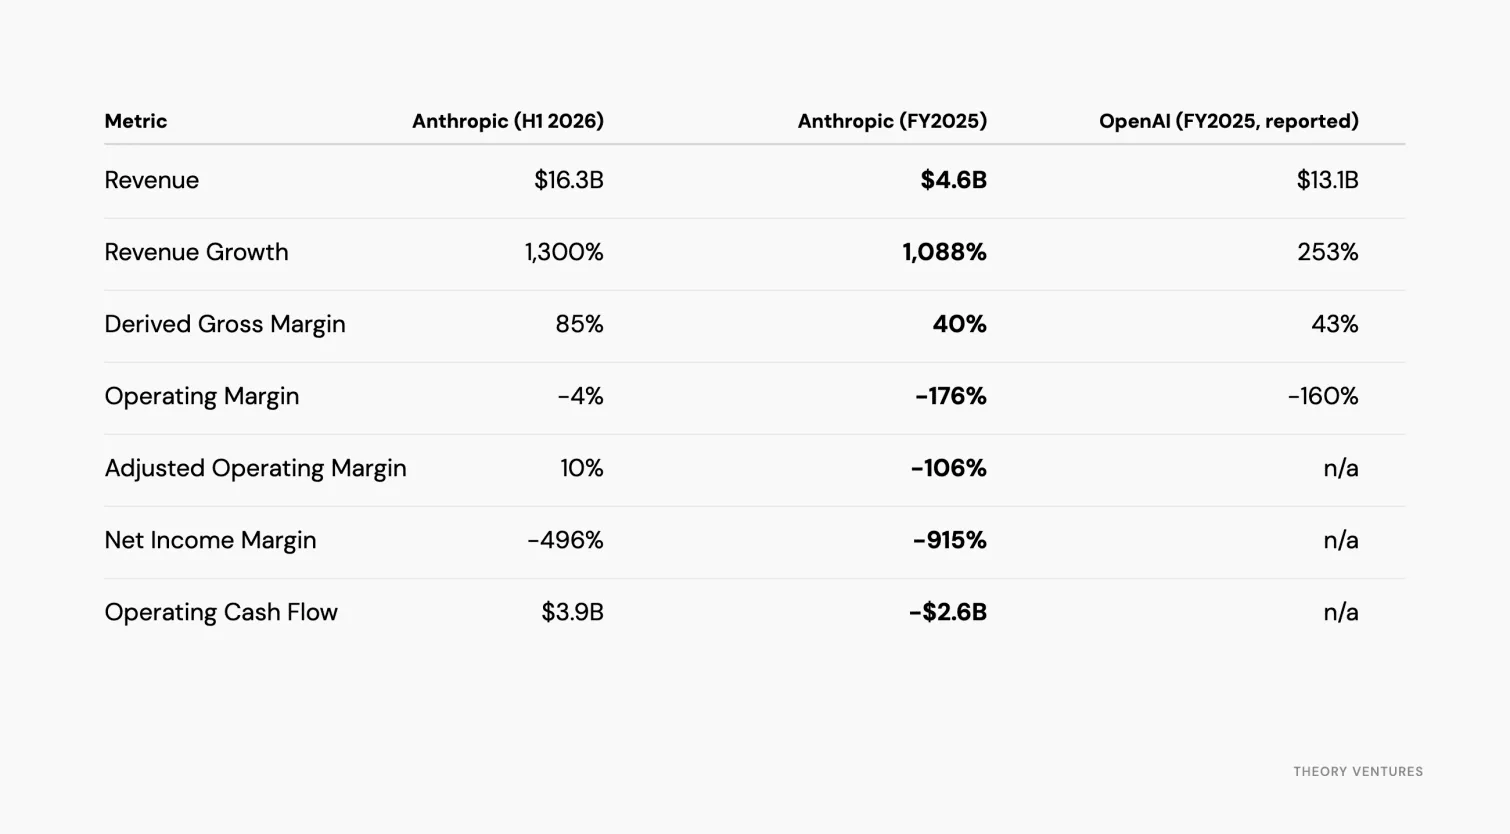
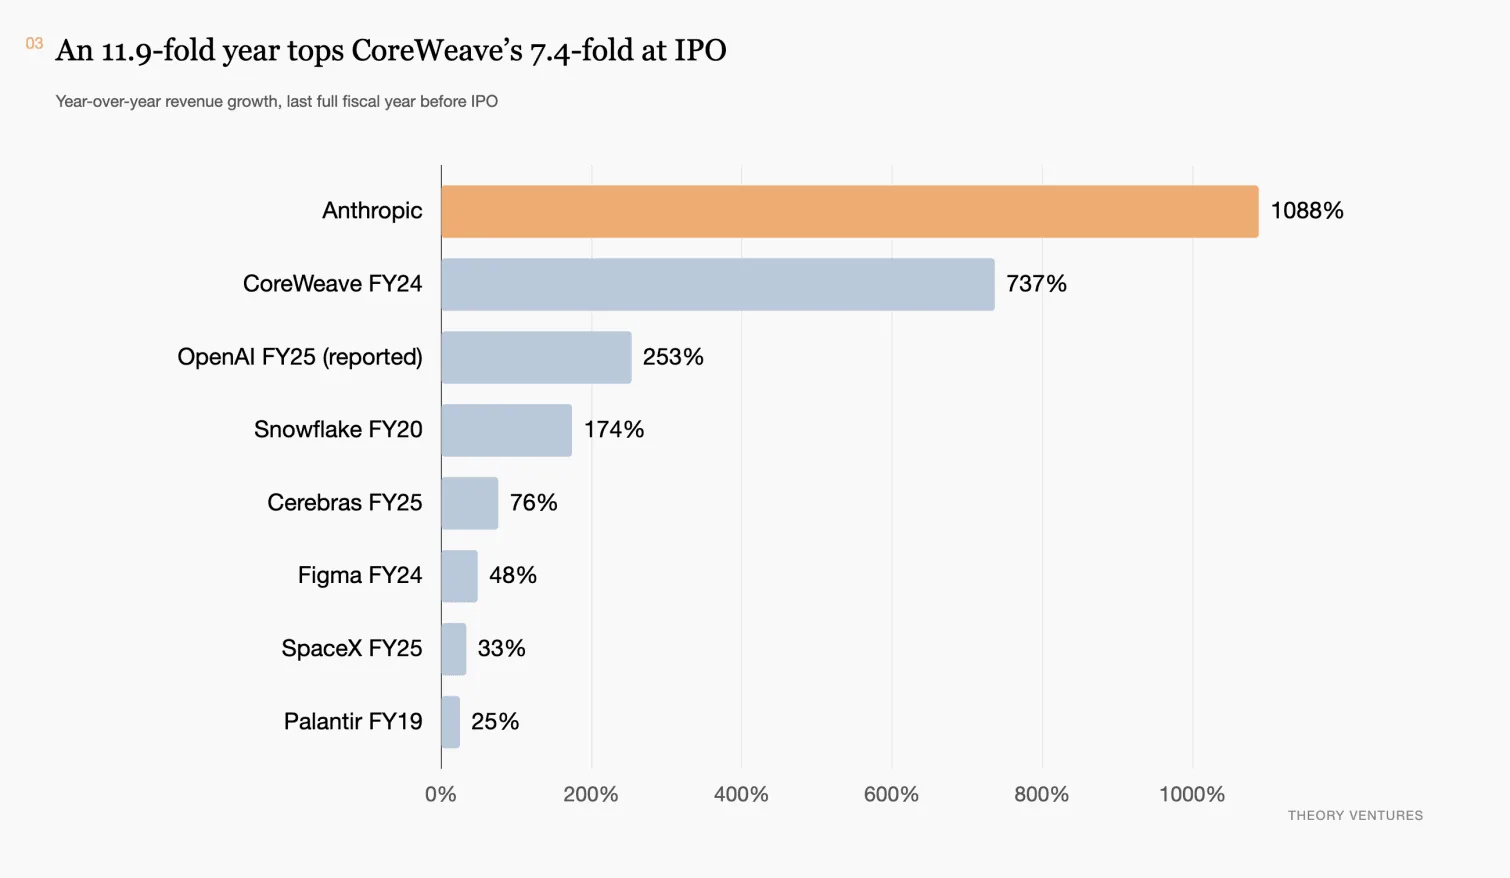
Anthropic generated $16.3B of revenue in the first six months of 2026, a fourteen-fold increase over the $1.2B of the first half of 2025. That half-year alone was more than three times all of 2025, when Anthropic grew 11.9-fold to $4.6B, more than four times OpenAI’s 253%.
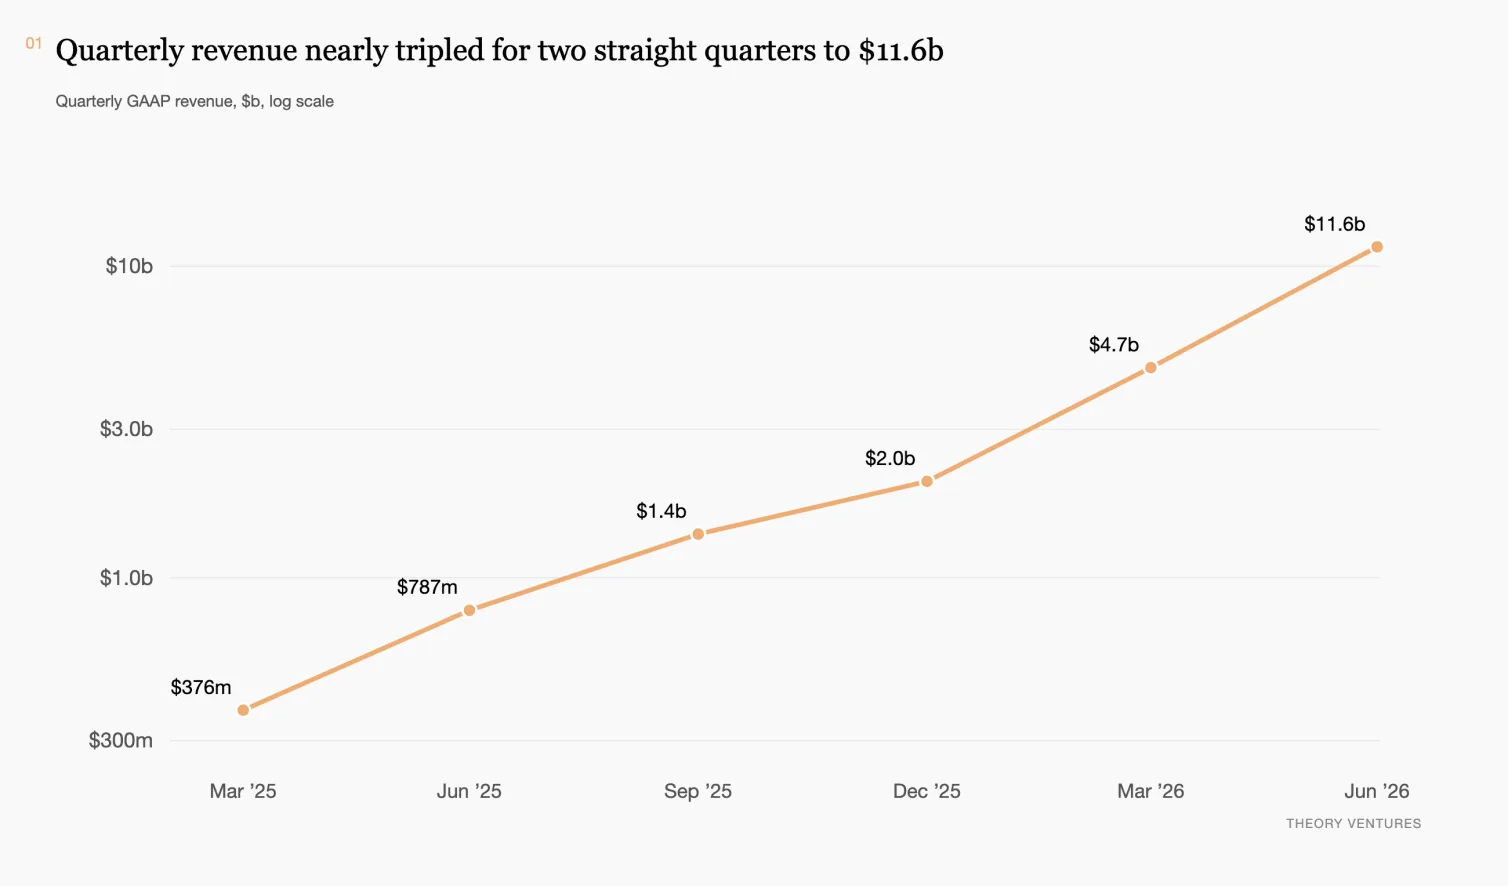
The second quarter was $11.6B against $4.7B in the first; revenue has nearly tripled for two consecutive quarters.
Three straight years of roughly ten-fold growth: 9.4x, then 11.9x, then 14.0x.
For example, with the release of Claude Fable 5.1 in September 2026, we reduced the cost of typical workloads by approximately 25% compared to Fable 5, with savings of up to 45% for complex coding & highly agentic tasks. Similarly, with the release of Opus 5.5 that same month, we reduced customers’ cost per task by approximately 40% compared to Opus 5.
When Opus 4.5 launched in November 2025 with more capability & a lower cost per task than Opus 4.1, revenue growth accelerated from 48% quarter over quarter to 132% the following quarter. Jevon’s paradox in the real world.
Anthropic is cash-flow positive. Operating loss was $8.1B in 2025 including a $1.5B copyright settlement. It narrowed every quarter of 2026, & in the second quarter Anthropic reported $974M of operating income, an 8.4% GAAP margin & 19% adjusted.
Anthropic has distributed its computing needs evenly over four major providers. Broadcom, SpaceXAI, Google & AWS each hold between $110B & $161B of commitments, together four fifths of the $637B total.

Anthropic carries essentially no drawn debt : the $15B revolver is undrawn & the only outstanding notes are $6.2B of non-interest-bearing Amazon convertibles. The leverage is instead in commitments. The filing discloses $265.6B of fixed or minimum guarantees at June 30, 2026 & a further $245B executed since.
These businesses are forming a keiretsu : each entangled in the other’s equity, debt & go-to-market.
Concentration has fallen : no single customer exceeded 10% of revenue for the nine months to September 30, 2026, & the top five were about 25%. That is different from 2025, when customers spending over $100,000 accounted for 76% of revenue.

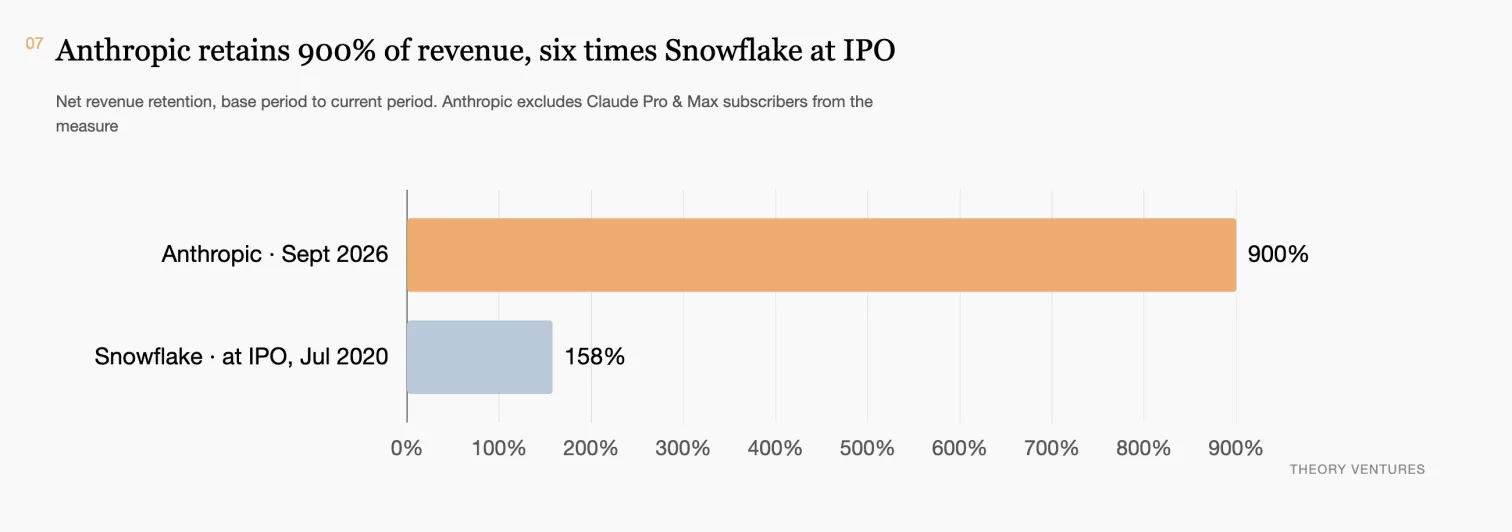
This pattern of initial deployment, demonstrated value, & rapid expansion has been replicated across organizations & is reflected in our Net Revenue Retention of approximately 900% as of September 30, 2026.
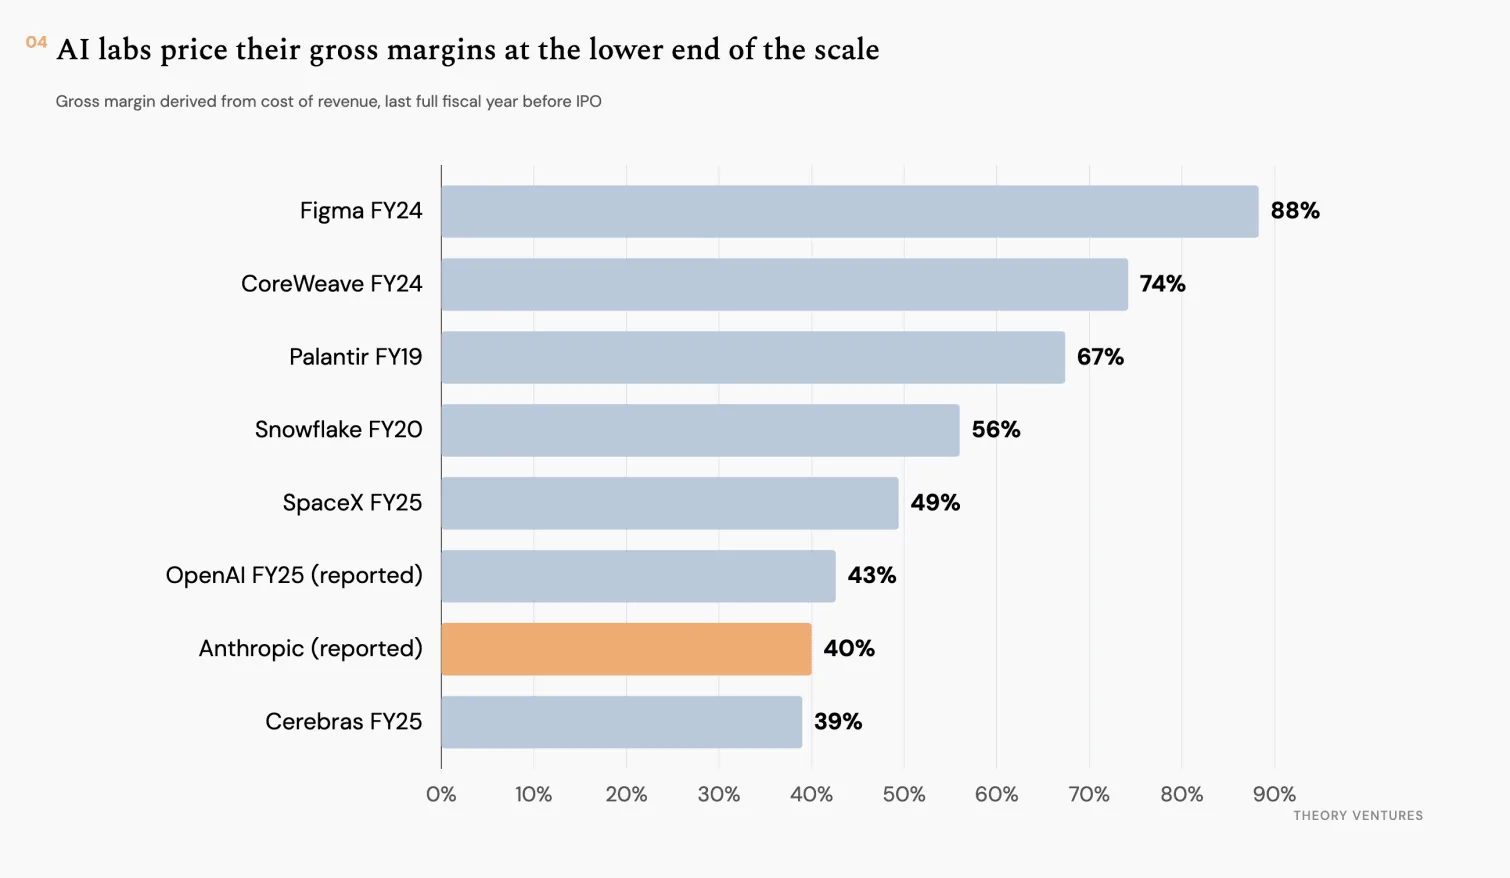
What is Anthropic worth? The case for a very large number is simple : a business that grew 11.9-fold on a 40% derived gross margin & has just begun earning an operating profit. The case against is equally simple : $637B of compute commitments, two thirds non-cancelable, against $4.6B of 2025 revenue, where revenue is consumption-based with no lock-in & the payments arrive whether customers do.
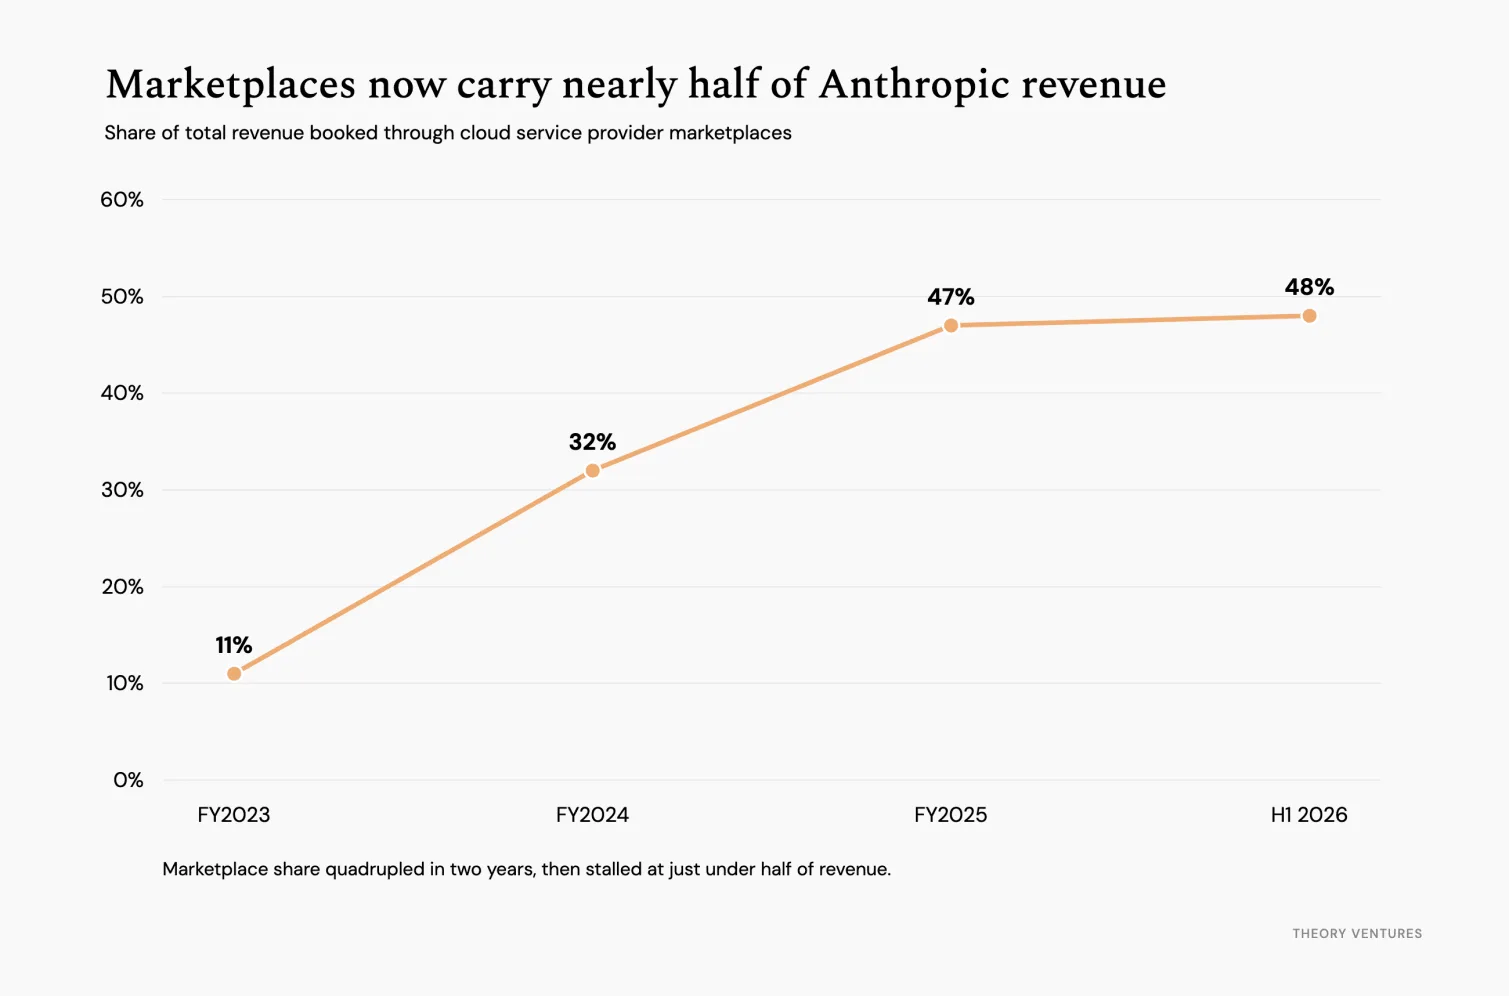
Nearly half of Anthropic revenue is now delivered through market places, a natural progression of many enterprise companies.

Anthropic’s S-1 describes an AI company with an enviable business model, explosive growth, & increasing efficiency.
Congratulations to the Anthropic team on reaching this milestone. Building a business that went from $41M to a $16B half-year in three years is without precedent.
-
Anthropic, PBC Form S-1, SEC EDGAR CIK 0002130357, accession 000162828026067168, filed October 26, 2026: https://www.sec.gov/Archives/edgar/data/2130357/000162828026067168/anthropicpbc-sx1.htm ↩︎
-
OpenAI figures are press-reported & unverified. Anthropic figures are from the S-1 filed October 26, 2026 (SEC EDGAR CIK 0002130357). ↩︎
-
Anthropic does not report gross margin. It changed in FY2025 from a functional presentation to one by nature of expense. The 40% is derived from Note 8, which retains cost of revenue: (4,585 - 2,773) / 4,585. The equivalent for the first half of 2026 is 85%: (16,286 - 2,380) / 16,286. Both are my calculations, not disclosed figures. ↩︎
-
Adjusted operating income excludes stock-based compensation, non-cash charitable contributions & the Bartz settlement. FY2025 adjusted operating loss was $4.9B against a GAAP $8.1B. ↩︎
-
The $637B of commitments is the sum of seven named agreements in the filing: Broadcom $161.2B, SpaceXAI up to $120.5B, Google at least $114.5B, Amazon at least $110.0B, Microsoft at least $44.9B, Nscale up to $44.6B & Lambda approximately $41.3B. The filing does not disclose an aggregate total; that figure is my arithmetic. Google, Amazon, Microsoft & Broadcom are “at least” commitments that are non-cancelable with true-up clauses. SpaceXAI may be cancelled by either party on 90 days’ notice after initial periods ending January & March 2027. Nscale & Lambda accrue fees only as capacity is delivered. ↩︎
Source: Tomasz Tunguz · tomtunguz.com